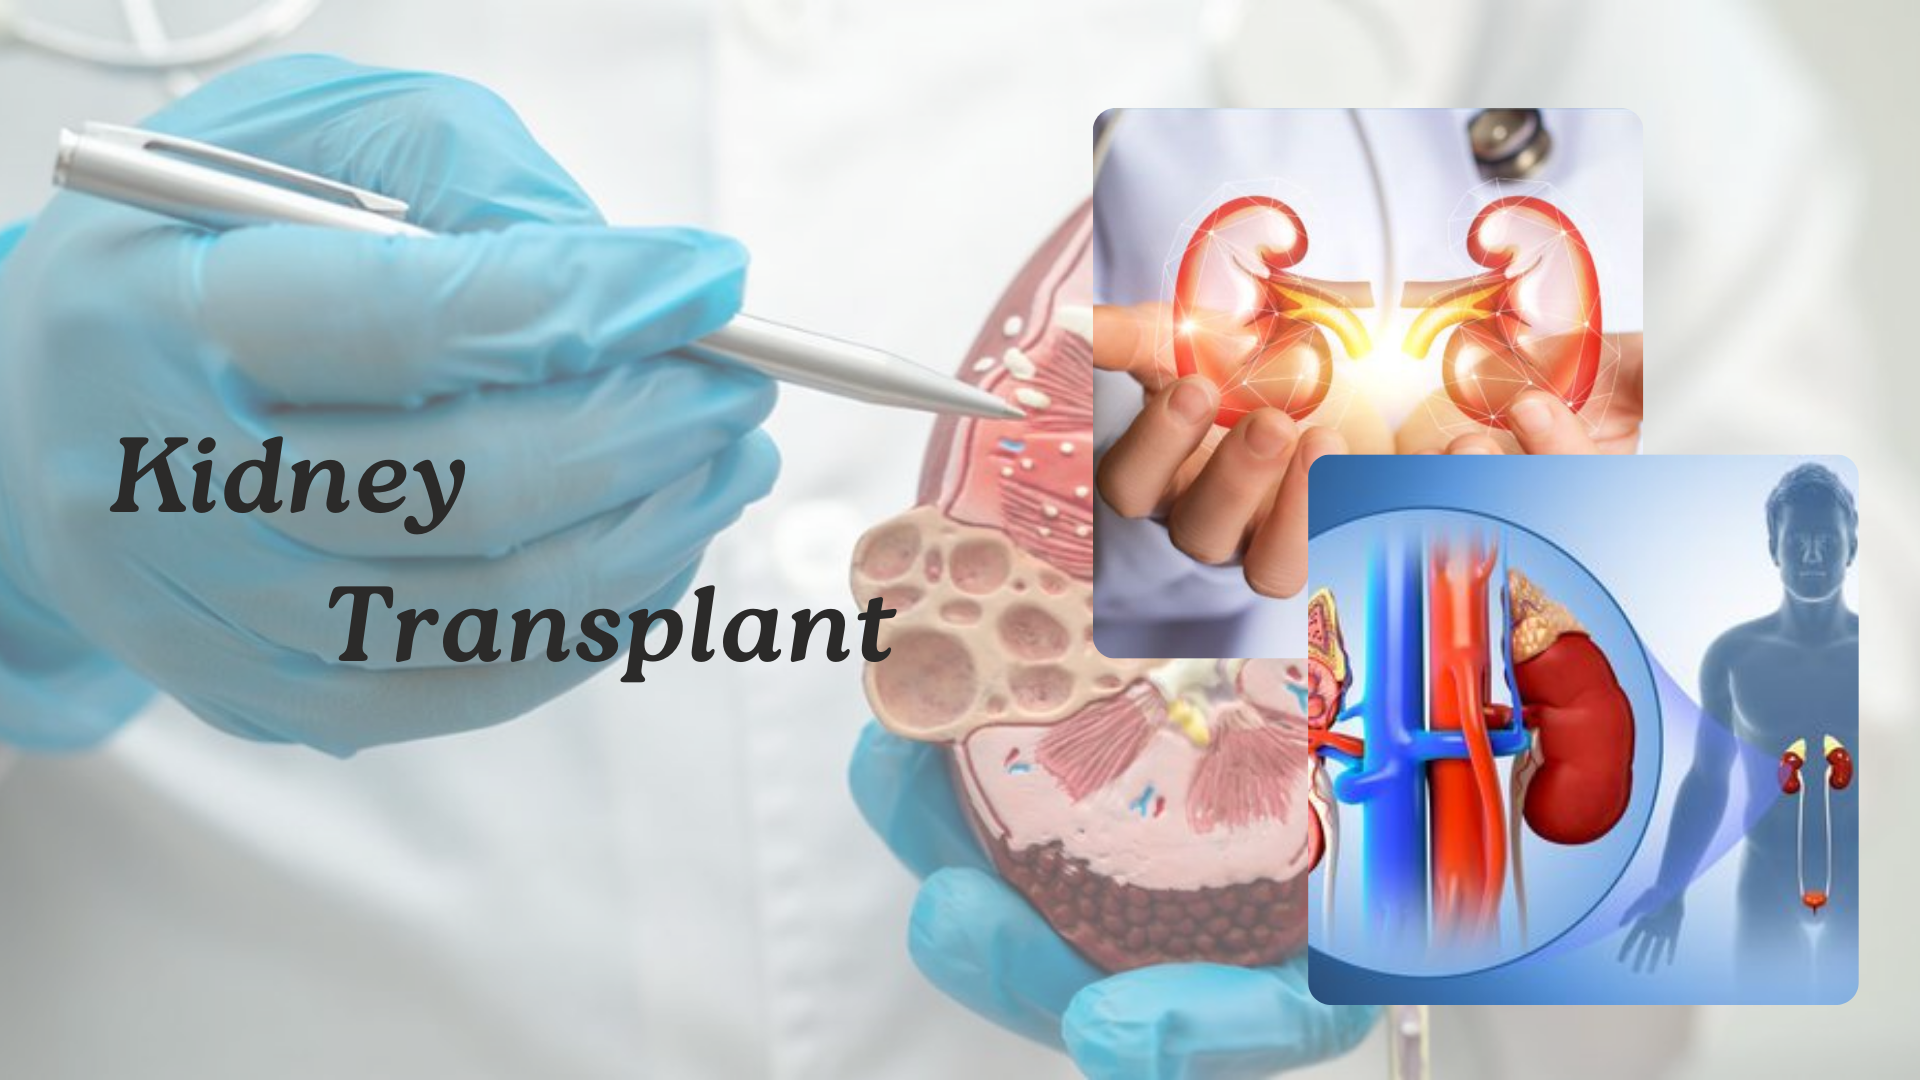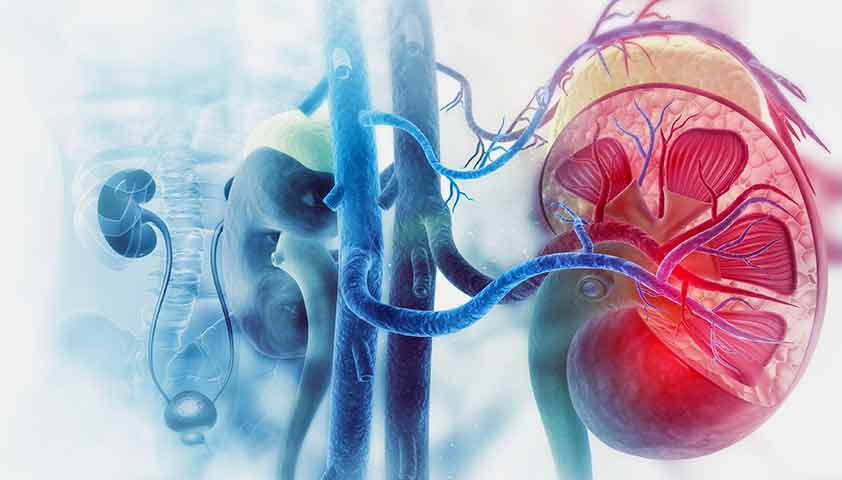
The Kidney Transplant Rejection Market encompasses a range of therapeutic and diagnostic solutions designed to prevent, detect, and treat immune-mediated graft failure following renal transplantation. Products include next-generation immunosuppressants, biologics targeting T-cell activation, gene-based therapies, and advanced diagnostics for real-time monitoring of donor–recipient compatibility. These offerings provide significant advantages—reduced incidence of acute and chronic rejection, fewer side effects compared with broad-spectrum immunosuppression, and personalized treatment regimens that improve long-term graft survival.
Kidney Transplant Rejection Market growing prevalence of end-stage renal disease, coupled with a persistent organ shortage, has heightened demand for more efficacious rejection-management strategies. Additionally, integration of molecular assays and noninvasive biomarkers enables early intervention and dose optimization, minimizing hospital stays and healthcare costs. Technological breakthroughs in genome editing, particularly CRISPR-based approaches, promise durable immune tolerance and targeted mitigation of alloimmune responses.
According to CoherentMI, The kidney transplant rejection market is estimated to be valued at USD 1.63 Bn in 2025 and is expected to reach USD 2.94 Bn by 2032, growing at a compound annual growth rate (CAGR) of 8.8% from 2025 to 2032.
Key Takeaways
Key players operating in the Kidney Transplant Rejection Market are
· Eledon Pharmaceuticals
· Sangamo Therapeutics
· AlloVir
· CSL Behring
· Hansa Biopharma
Significant opportunities lie in emerging economies, where expanding healthcare infrastructure and rising transplant volumes create new markets for advanced anti-rejection solutions. Personalized immunosuppressive protocols, facilitated by AI-driven risk stratification and telemonitoring platforms, can further optimize dosing and adherence, reducing graft loss. Collaborations between biotech firms and transplant centers are expected to accelerate clinical validation and market penetration of novel therapies.Technological Advancement: CRISPR-based gene editing is revolutionizing the management of transplant rejection by enabling precise modification of donor tissues and engineering regulatory immune cells. This approach holds the potential to induce long-term graft tolerance, reduce lifelong dependence on systemic immunosuppression, and minimize off-target effects, thereby driving market growth.
Market Drivers
The foremost driver of the Kidney Transplant Rejection Market is the escalating burden of end-stage renal disease (ESRD) worldwide, fueled by diabetes, hypertension, and aging populations. As dialysis remains a suboptimal long-term solution, kidney transplantation offers superior survival and quality-of-life benefits, leading to a steady increase in transplant procedures. However, alloimmune rejection continues to pose significant clinical challenges, resulting in graft loss, repeated interventions, and elevated treatment costs. This clinical imperative propels demand for innovative anti-rejection therapies that can extend graft longevity and reduce hospital readmissions. Additionally, regulatory incentives and streamlined approval pathways for breakthrough biologics and gene therapies have lowered barriers to market entry, encouraging investment in R&D. Advances in diagnostic assays—encompassing donor-derived cell-free DNA and transcriptomic profiling—enable early detection of subclinical rejection, prompting timely therapeutic adjustments. Collectively, the rising transplant volume, critical need for better graft outcomes, and technological enablers constitute the principal market drivers sustaining robust growth through 2032.
Challenges, SWOT Overview and Geographic Landscape
The kidney transplant rejection arena faces several hurdles. Early detection of immune responses remains difficult due to the subtlety of biomarkers, leading to delayed intervention. Limited access to advanced diagnostic platforms in resource-constrained settings impedes timely monitoring of graft function. Patient adherence to complex immunosuppressive regimens often falters because of side-effect profiles and multiple daily dosing schedules. Financial constraints and reimbursement complexities further hamper uptake of novel therapies. Regulatory pathways for next-generation immunomodulators are intricate, prolonging development timelines and increasing uncertainty for innovators. Finally, variability in genetic and immunological profiles across patient populations complicates the design of universal treatment protocols.
Geographic Regions
North America accounts for a significant concentration of therapeutic activity and clinical research due to well-established transplant centers, robust reimbursement frameworks, and high healthcare spending per capita. Western Europe also maintains a strong presence, supported by centralized health systems that streamline patient access and real-world evidence generation. Regulatory and reimbursement mechanisms in key Asian markets (e.g., Japan, South Korea) have recently been optimized for expedited review of advanced therapies, encouraging local trials. Emerging economies in Latin America and parts of the Middle East & Africa show growing demand, but infrastructural gaps limit broad deployment of specialized services. Investments in laboratory capabilities, clinician training, and patient support programs will be crucial to expand reach and ensure equitable access.
Current Challenges
The kidney transplant rejection field grapples with multiple immediate obstacles. First, existing immunosuppressive regimens often require lifelong administration, and their cumulative toxicity can heighten risks of infection, malignancy, and metabolic complications. This undermines long-term patient outcomes and strain post-transplant care resources. Diagnostic hurdles remain acute: routine monitoring via serum creatinine or biopsy may detect rejection only after significant tissue injury, missing opportunities for early intervention. Noninvasive biomarkers are emerging but require broader validation before routine clinical use. Geographic disparities in healthcare infrastructure mean many patients in low- and middle-income regions cannot access specialized testing or advanced therapies. Financial barriers and uneven insurance coverage further restrict patient enrollment in clinical trials and access to novel modalities. Regulators demand extensive safety and efficacy data for immunomodulatory agents, elongating development timelines and inflating costs. Moreover, patient education and adherence support are often under-resourced, leading to suboptimal dosing compliance. Addressing these challenges will require cross-disciplinary collaboration among clinicians, researchers, payers, and patient advocacy groups.
SWOT AnalysisStrength:•
Robust scientific advances in immunogenetics have led to more precise targeting of rejection pathways, enhancing therapeutic specificity and reducing off-target effects.• Established transplant centers and collaborative research networks accelerate clinical trial enrollment and facilitate multi-center data sharing.
Weakness:• Reliance on invasive biopsy remains common practice, delaying rejection detection until significant graft injury has occurred.• High variability in patient immune profiles complicates standardization of dosing regimens, leading to suboptimal outcomes in heterogeneous populations.
Opportunity:•
Emerging liquid-biopsy technologies (e.g., donor-derived cell-free DNA assays) promise real-time, noninvasive monitoring of graft integrity, enabling earlier therapeutic adjustments.• Digital adherence platforms and telemedicine support can help patients maintain complex medication schedules, reducing episodes of noncompliance.
Threats:• Alternative graft sources, such as xenotransplants and bioengineered tissues, could shift clinical practice away from current immunosuppressive approaches.• Safety concerns or high-profile adverse events involving new immunomodulators may undermine physician and patient confidence, slowing adoption of novel agents.
Geographical Regions Where Market Value Is Concentrated
Significant value concentration resides in North America and Western Europe. In North America, leading transplant centers, high per-capita healthcare spending, and supportive reimbursement policies create a fertile environment for both established therapies and innovative diagnostics. Clinical research infrastructure is robust, with streamlined regulatory pathways facilitating early‐phase and pivotal trials. Europe’s centralized health authorities and pan‐European cooperative initiatives enable rapid real-world data collection and post-market surveillance, reinforcing commercial viability.
Japan and South Korea in the Asia-Pacific also hold considerable value share due to government incentives for regenerative medicine and advanced diagnostics. These markets feature mature hospital systems, strong investments in biotech, and patient populations that readily adopt cutting-edge interventions. Although markets in Latin America, the Middle East, and Africa are smaller in absolute terms, ongoing infrastructure development and rising incidence of chronic kidney disease hint at future value growth if diagnostic and therapeutic access expand.
Fastest Growing Region
The Asia-Pacific region is emerging as the fastest growing territory for kidney transplant rejection management. Rapid enhancements in healthcare infrastructure—particularly in China, India, and Southeast Asia—have spurred demand for advanced diagnostics and targeted therapies. Governments across the region are increasing budget allocations for noncommunicable diseases, including chronic kidney conditions, and are implementing policies that expedite regulatory reviews for breakthrough medical technologies.
The prevalence of end-stage renal disease is climbing, driven by aging populations and rising rates of diabetes and hypertension. In parallel, collaborations between local biotech firms and global research organizations have accelerated clinical trial activity, bringing innovative immunosuppressive agents and monitoring tools to market more quickly. Telemedicine platforms are also gaining traction, supporting remote monitoring and adherence, a crucial component in vast, rural areas. Altogether, these factors are propelling Asia-Pacific to lead in growth rate, promising a dynamic environment for both established players and emerging innovators.
➢Get this Report in Japanese Language: 腎臓移植拒絶反応市場
➢Get this Report in Korean Language: 신장이식거부시장
About Author:
Ravina Pandya, Content Writer, has a strong foothold in the market research industry. She specializes in writing well-researched articles from different industries, including food and beverages, information and technology, healthcare, chemical and materials, etc. (https://www.linkedin.com/in/ravina-pandya-1a3984191)
Organ Transplant Rejection Medications Market: IntroductionAccording to the report, the global organ transplant rejection medications market was valued at US$ 4.7 Bn in 2018 and is projected to expand at a CAGR of ~3% from 2019 to 2027.
Increase in per capita disposable income is encouraging people to spend more on healthcare facilities, which, in turn, fuels the global organ transplant rejection medications market.
Advertisements have increased public visibility of new technology, thereby generating interest among chronic patients for organ transplant rejection medications.Changing demographics in emerging economies such as China, India, Brazil, and South Africa are expected to provide significant opportunities for organ transplant rejection medications.
It is comparatively more cost-effective than dialysis and is associated with a long-term mortality improvement.Based on distribution channel, the global organ transplant rejection medications market has been classified into hospital pharmacies, retail pharmacies, and online pharmacies.
Hospitals are major clinical settings wherein a large number of surgeries are conducted.
These include GlaxoSmithKline plc, Novartis AG, F. Hoffmann-La Roche Ltd., Astellas Pharma, Inc., Pfizer, Inc., AbbVie, Inc., Allergan plc, Bristol-Myers Squibb Company (BMS), and Sanofi.Novartis AG is a leading company that specializes in the development and manufacture of branded as well as generic pharmaceutical and biopharmaceutical drugs.