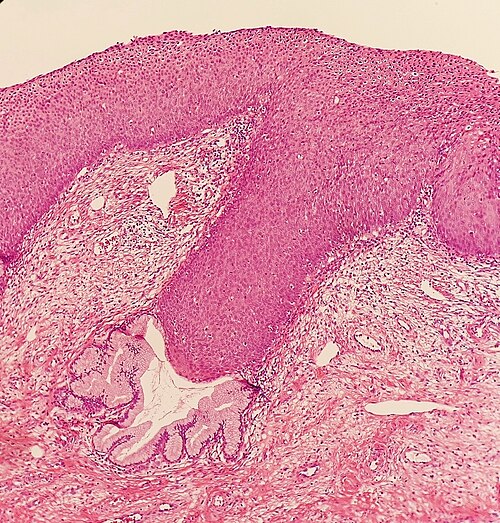
The Cervical Intraepithelial Neoplasia (CIN) market encompasses diagnostic and therapeutic products used in early detection and treatment of precancerous cervical lesions. Key offerings include HPV DNA tests, high-resolution colposcopes, biopsy kits, and cryotherapy devices, all designed for high sensitivity, minimal invasiveness, and improved patient comfort.
Cervical Intraepithelial Neoplasia Market As the incidence of HPV-related cervical abnormalities rises and preventative healthcare gains priority, accurate and timely diagnosis becomes essential to reduce morbidity and healthcare costs. Favorable reimbursement policies and expanding research initiatives further drive adoption of advanced CIN solutions. Enhanced screening not only facilitates early intervention but also contributes to better long-term outcomes.
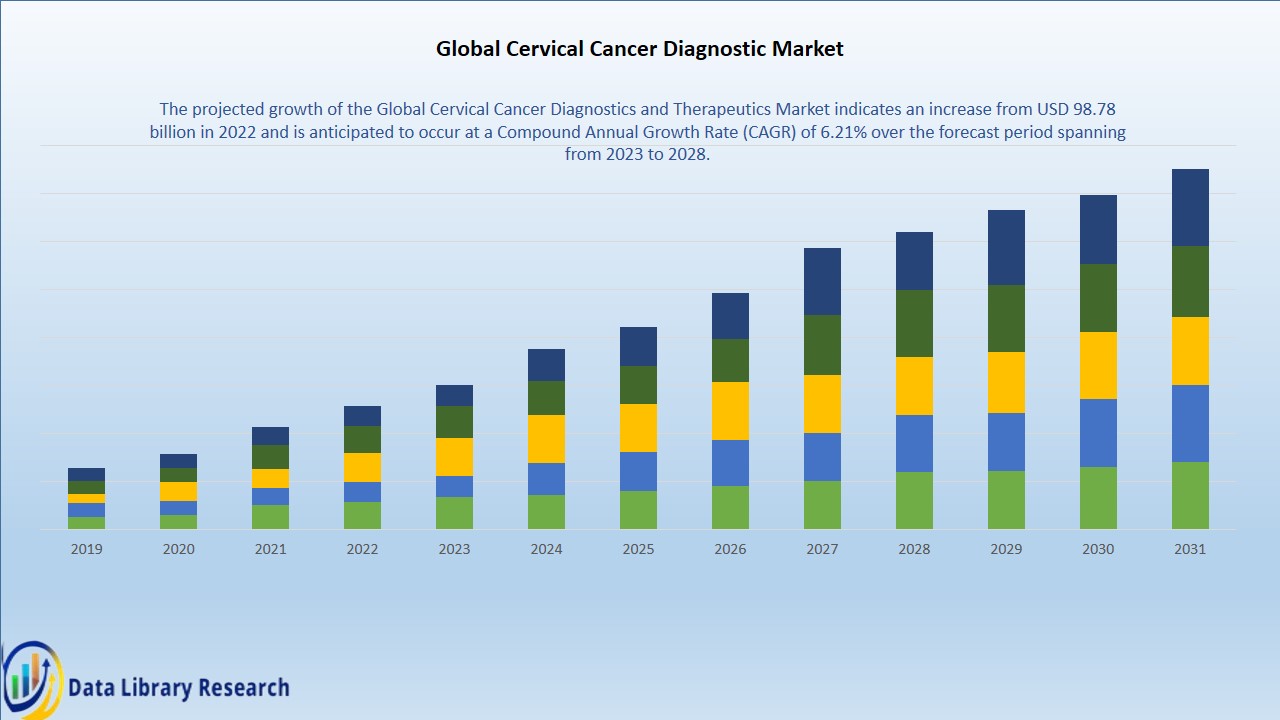
The Global Cervical Intraepithelial Neoplasia Market is estimated to be valued at USD 706.3 Mn in 2025 and is expected to reach USD 1020.6 Mn by 2032, growing at a compound annual growth rate (CAGR) of 5.4% from 2025 to 2032.
Key Takeaways
Key players operating in the Cervical Intraepithelial Neoplasia Market are Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Johnson & Johnson Private Limited, and Merck & Co., Inc. These major players shape market share through extensive product portfolios and global distribution networks. Their strategic collaborations and mergers generate deep market insights, enhancing competitive edge and enabling broader access to advanced CIN diagnostics and therapeutics.The growing demand for minimally invasive diagnostic solutions and targeted therapies is a primary catalyst for market growth. Increased awareness campaigns, community screening programs, and supportive health policies have boosted patient participation rates globally. Rising healthcare expenditure, especially in emerging regions, expands market size and underscores the importance of reliable, cost-effective CIN management tools.Technological advancement is at the forefront of CIN market evolution. AI-assisted image analysis in colposcopy, point-of-care molecular assays, and next-generation sequencing platforms enhance diagnostic precision and reduce turnaround times. These innovations streamline clinical workflows, improve lesion detection accuracy, and foster patient compliance. As digital health integration intensifies, mobile screening units and telecolposcopy services are set to redefine treatment pathways and expand reach in underserved areas.
Market Trends
Two key trends are shaping the CIN market. First, expanding cervical cancer screening programs, backed by government initiatives and non-profit organizations, are driving early detection rates upward. Increased funding for HPV testing and public awareness campaigns is a defining market trend that fuels demand for advanced diagnostic kits. Second, the integration of artificial intelligence and machine learning in cytology and colposcopy analysis improves diagnostic accuracy and minimizes inter-observer variability. AI-driven software provides real-time interpretation of cervical images, aiding clinicians in identifying high-grade lesions and optimizing patient management strategies.
Market Opportunities
Emerging regions in Asia-Pacific and Latin America offer significant market opportunities, driven by rapid urbanization, improved healthcare infrastructure, and rising public health investments. Opportunities exist to introduce cost-effective screening solutions and expand treatment access through public-private partnerships. Additionally, the move toward personalized medicine—featuring biomarker-based risk stratification and HPV-targeted vaccines—opens new avenues for product differentiation. Collaborations between diagnostic developers and biotech firms to create immunotherapeutic approaches represent a lucrative opportunity, fostering innovative segments and accelerating revenue growth.
Impact of COVID-19 on Cervical Intraepithelial Neoplasia Market Growth
The onset of the COVID-19 pandemic significantly disrupted routine screening and treatment pathways for cervical intraepithelial neoplasia (CIN). Pre-COVID, organized public health initiatives emphasized regular cytology and HPV testing with robust patient follow-up. During lockdowns and resource reallocation, many outpatient clinics scaled back elective procedures and deferred colposcopies, leading to diagnostic delays. Clinical laboratories shifted focus toward SARS-CoV-2 testing, causing backlog in pathology workflows. These interruptions introduced new market challenges, as reduced patient visits and postponed preventive care temporarily dampened growth momentum. As the acute phase of the pandemic waned, healthcare systems began ramping up targeted CIN screening campaigns. There was an accelerated adoption of telemedicine consultations, enabling preliminary assessments and triage. Remote patient monitoring tools and digital reminders improved appointment adherence, highlighting a key market driver: digital health integration. Meanwhile, renewed emphasis on catch-up screening generated notable market opportunities for innovative diagnostic devices and point-of-care solutions. Looking ahead, future strategies must build resilience in care delivery. Stakeholders should incorporate flexible scheduling models and mobile screening units to reach under-screened populations. Strengthened supply chain risk management will ensure uninterrupted access to critical reagents and medical disposables. Ongoing market research is essential to anticipate shifts in patient behavior and policy changes, while market insights can guide investment in AI-driven image analysis and self-sampling kits. Addressing both market restraints—such as patient hesitancy—and emerging digital transformation will be key to sustaining long-term business growth in the CIN space.
Geographical Regions with High Value Concentration
In terms of value concentration, North America remains a focal point for cervical intraepithelial neoplasia interventions. Well-established reimbursement frameworks, extensive public awareness campaigns, and widespread adoption of advanced screening technologies contribute to a significant share of global demand. The robust healthcare infrastructure supports high throughput of cytology labs, driving consistent utilization of diagnostic and therapeutic solutions. Europe follows closely, with leading markets in Western and Northern Europe. National screening guidelines and government-funded programs ensure regular uptake of HPV testing and colposcopic evaluations. Advanced research institutions and strong regulatory support foster continuous innovation, underpinning market dynamics favoring premium devices and treatment modalities. Within the Asia Pacific region, Japan and Australia exhibit high value concentration due to early integration of HPV vaccination and state-sponsored screening initiatives. While some emerging APAC economies lag in coverage, key urban centers in China and South Korea are investing heavily in diagnostic infrastructure, driving urban market clusters. Latin America and the Middle East also represent notable pockets of concentrated demand. In select countries, partnerships between public health agencies and private diagnostic firms have expanded screening outreach, elevating the regional market scope. Overall, regions with established healthcare funding mechanisms and organized prevention programs display the greatest value density in the CIN market.
Fastest-Growing Region for Cervical Intraepithelial Neoplasia Market
Asia Pacific stands out as the fastest-growing region, propelled by increasing awareness of women’s health issues, expanding screening campaigns, and rising healthcare expenditure. Many APAC governments have recently updated national guidelines to include HPV DNA testing alongside traditional cytology, creating a surge in demand for advanced diagnostic platforms. Rapid urbanization and improving access to specialty clinics in China and India have opened substantial market opportunities for both established and emerging players. In India, public-private collaborations have launched mobile screening vans and self-sampling kits, overcoming rural access barriers. This innovative approach illustrates a key market trend toward decentralization of care. Similarly, Southeast Asian countries such as Thailand and Indonesia are integrating telemedicine services for follow-up consultations, increasing patient adherence and detection rates. These digital initiatives are crucial market drivers, accelerating adoption of remote diagnostic tools and laboratory automation. Latin America is also exhibiting robust growth rates, particularly in Brazil and Mexico, where national vaccination rollouts and cervical cancer awareness programs have gained momentum. Partnerships with international NGOs and domestic foundations fuel training programs for gynecologists and cytotechnologists, enhancing regional capabilities. Furthermore, the Middle East and Africa are emerging as high-growth corridors. Investments in healthcare infrastructure, along with donor-funded screening initiatives in Sub-Saharan Africa, are expanding diagnostic reach. Pilot projects using portable colposcopes and smartphone-based imaging reinforce market trends toward affordable point-of-care solutions. In these regions, targeted education campaigns and subsidized testing are anticipated to drive sustained growth, positioning them among the fastest-expanding markets globally.
Get more insights on: Cervical Intraepithelial Neoplasia Market
Get this Report in Japanese Language: 子宮頸部上皮内腫瘍市場
Get this Report in Korean Language: 자궁경부상피내종양시장
About Author:
Ravina Pandya, Content Writer, has a strong foothold in the market research industry. She specializes in writing well-researched articles from different industries, including food and beverages, information and technology, healthcare, chemical and materials, etc. (https://www.linkedin.com/in/ravina-pandya-1a3984191__