

Thinking about purchasing a manufactured home in the Lone Star State? You're not alone. As home prices continue to rise, manufactured housing is quickly becoming a popular choice. But one essential factor to understand before purchasing is how to secure financing. That’s where manufactured home lenders in Texas come in.
Unlike traditional mortgages, loans for manufactured homes come with specific guidelines, programs, and lender qualifications. This article will walk you through everything you need to know about manufactured home loans in Texas, from eligibility requirements and loan types to how to choose the right lender.
What Are Manufactured Homes?
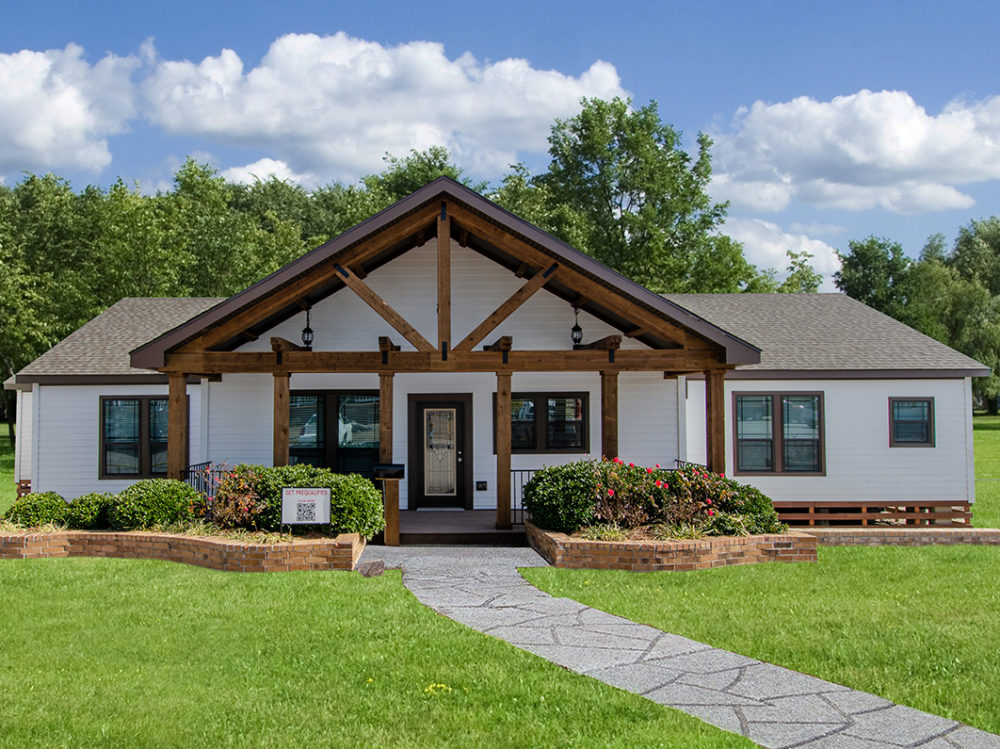
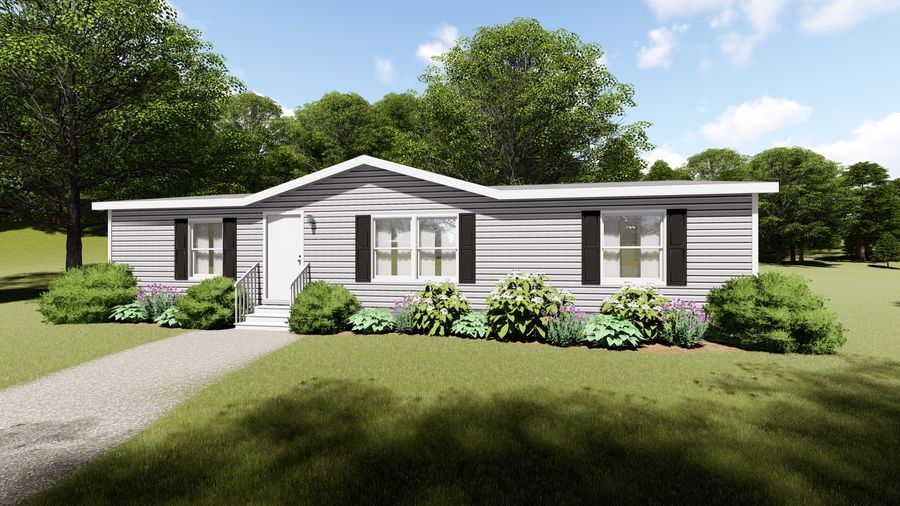
Manufactured homes are prefabricated homes built in a factory and then transported to a designated location. Unlike modular homes, which are pieced together on-site, manufactured homes are fully assembled prior to delivery and must comply with the HUD Code established in 1976. This federal code ensures the home meets certain standards for strength, durability, transportability, fire resistance, energy efficiency, and overall quality.
Today’s manufactured homes are far from the old-fashioned “mobile homes” of the past. Modern units come with updated amenities like high-quality finishes, energy-efficient systems, and customizable floor plans—at a fraction of the cost of site-built homes.
Why Manufactured Homes Are a Smart Option in Texas
Texas has long been a favorable market for manufactured homes, thanks to:
Manufactured homes offer a fast, affordable solution for individuals and families who want to own a home without getting buried in debt. Whether you're settling in East Texas piney woods, the Hill Country, or wide-open West Texas, a manufactured home can provide comfort and stability without breaking the bank.
Loan Basics: How Do Manufactured Home Loans Work?
Financing a manufactured home differs depending on how the home is installed and whether or not you also own the land.
Chattel Loans
These are personal property loans used when the home is not attached to land. These loans generally:
Real Property Loans
If the manufactured home is permanently affixed to land that you own, you may be eligible for a mortgage similar to one used for site-built homes. These loans typically:
Manufactured home lenders in Texas offer both chattel and real property loans, depending on your situation.
Types of Manufactured Home Loans in Texas
1. FHA Loans
Insured by the Federal Housing Administration, these loans are ideal for low-to-moderate-income borrowers.
Pros:
2. VA Loans
Available to eligible veterans, active-duty service members, and their families.
Benefits:
3. USDA Loans
Designed for rural housing, USDA loans are perfect for manufactured homes in qualified areas.
Features:
4. Conventional Loans
Fannie Mae and Freddie Mac offer conventional loans for manufactured homes—but with stricter requirements.
Requirements:
5. In-House Financing
Some lenders and home retailers offer their own financing solutions.
Caution:
Loan Eligibility Requirements
To qualify for a manufactured home loan, you’ll need to meet basic eligibility criteria:
Pro tip: Pre-qualify early so you know where you stand and can shop confidently.
Mobile Home Financing in Texas: Understanding the Nuances
It’s important to understand that mobile home financing in Texas includes financing options for both mobile homes built before June 15, 1976 (which may be harder to finance) and modern HUD-compliant manufactured homes.
Lenders will evaluate:
Because mobile home financing requires careful review, always work with a lender who specializes in manufactured housing and knows Texas-specific requirements.
How to Choose the Right Manufactured Home Lender in Texas
Choosing the right lender is one of the most important steps in your manufactured home buying journey. While many financial institutions offer home loans, not all are equipped to handle the unique requirements and nuances of manufactured housing. Working with a lender that specializes in this type of financing can make a significant difference in the terms you receive, the speed of the process, and your overall satisfaction.
Here are the key factors to consider when selecting the best manufactured home lender in Texas:
1. Specialization in Manufactured and Mobile Home Loans
Not every lender deals with manufactured or mobile home financing. Some specialize solely in conventional, site-built home mortgages and may not fully understand the complexities of manufactured housing—especially when it comes to chattel loans, foundation requirements, or whether the home is considered real or personal property.
Look for lenders who:
Regularly work with manufactured home buyers
Offer a variety of financing solutions including FHA, VA, USDA, and chattel loans
Have a proven track record of success in the Texas market
A specialized lender will not only guide you through the loan process but also help you understand what programs you qualify for based on your property type and financial situation.
2. Texas Market Experience
Manufactured home financing can vary significantly by state due to differences in regulations, land use laws, and zoning. That’s why it’s crucial to work with a lender who is familiar with Texas-specific laws and housing trends.
An experienced Texas lender will:
Understand local zoning and land ownership laws
Help you navigate land-home packages or leased land financing
Provide insight into regional market rates and competitive offers
Be aware of any Texas-exclusive loan assistance programs or property tax benefits
Their local expertise can help you avoid common pitfalls and speed up the approval and closing process.
3. Loan Program Variety
Manufactured homes can be financed in several different ways depending on your needs. A good lender will offer flexible financing options to fit a range of borrower profiles and property types.
Choose a lender that provides:
Government-backed loans (FHA, VA, USDA) for lower down payments and easier qualification
Conventional loans for borrowers with strong credit and land ownership
Chattel loans for homes not affixed to permanent foundations
In-house financing for faster, more flexible approvals (with caution on rates)
Having multiple options allows you to compare and choose the best loan that matches your goals—whether that’s a lower monthly payment, minimal upfront cost, or faster closing.
4. Transparent Loan Terms and Fees
Clear communication is critical. Before you sign any paperwork, you should understand exactly what you're agreeing to—including interest rates, repayment terms, monthly payments, fees, and penalties.
Ask these important questions:
A reliable lender will walk you through all of these details openly, without pushing you toward options you’re uncomfortable with. Avoid lenders who are vague about fees or rush you into decisions.
5. Easy Pre-Approval and Application Process
A good manufactured home lender should offer an easy-to-navigate pre-approval process. Getting pre-approved early gives you a clear picture of how much you can borrow and what your payments might look like, empowering you to shop for homes within your budget.
Look for lenders that offer:
Some lenders even provide a pre-approval letter, which strengthens your offer when negotiating with sellers or home dealers.
6. Strong Customer Service and Support
Customer support often sets great lenders apart from the rest. You want a loan officer or team who is accessible, responsive, and willing to educate you throughout the process.
Choose a lender who:
Read online reviews and testimonials to get a sense of other borrowers’ experiences. Consistent praise for communication and professionalism is a strong sign you're in good hands.
7. Competitive Rates and Terms
While manufactured home loans can have slightly higher interest rates than traditional mortgages, the differences shouldn’t be extreme. Compare loan offers from at least two to three lenders before making your final decision.
Look for:
A lender who explains why a rate is offered—and how you might qualify for a better one in the future—is someone who has your best interests in mind.
8. Reputation and Licensing
Before you commit, verify that the lender is:
A Trusted Manufactured Home Lender in Texas
Clear Lending is a reputable financing provider specializing in loans for manufactured homes across Texas. Whether you're purchasing your first home, refinancing, or upgrading to a larger property, Clear Lending offers customized solutions that match your needs.
Why Clear Lending Stands Out:
If you're searching for a lender with experience, transparency, and customer-first service, Clear Lending should be at the top of your list.
Tips to Improve Your Chances of Loan Approval
Want to boost your chances of loan approval and secure better terms? Follow these tips:
Review Your Credit: Dispute any errors on your credit report and pay down debts.
Save for a Down Payment: Even if not required, it shows financial responsibility.
Avoid Big Purchases: Hold off on financing cars or making large credit card charges before applying.
Organize Financial Documents: Have pay stubs, tax returns, and ID ready.
Shop Multiple Lenders: Comparing rates can save you thousands over the life of your loan.
Final Thoughts
If you're ready to settle into an affordable, stylish, and modern home, manufactured housing might be your perfect fit. The key to making that dream a reality is working with trusted manufactured home lenders in Texas who understand your goals and offer financing tailored to your situation.
From FHA and VA loans to USDA and in-house programs, the right lender will walk with you every step of the way—from application to closing. Be sure to do your research, compare offers, and choose a financing partner like Clear Lending to help guide your journey.