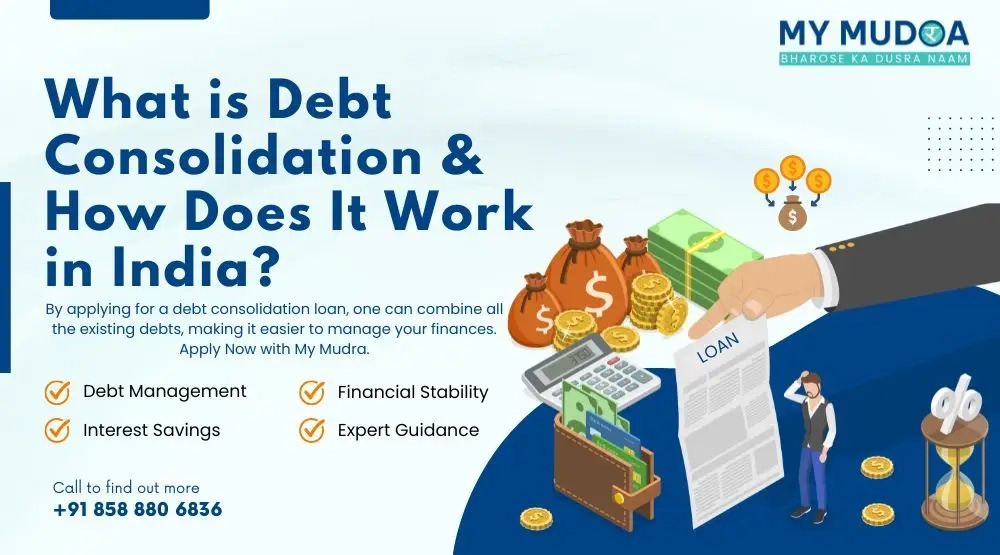
Debt consolidation can reduce the number of monthly payments without necessarily reducing the total cost. The outcome depends on interest rate, fees, repayment term and what happens to the old credit lines afterward. It is a useful reminder that the product has to work in context, not just look right on paper, and the practical check here is tied to fees. For buyers looking at Hong Kong debt consolidation loan, this is a better starting point than asking which option has the longest feature list. A smaller monthly payment can feel like savings even when the total cost has increased. The useful question is what has to remain true once the product or service leaves the demo environment and enters normal use, and the practical check here is tied to effective borrowing cost.
Start with the real job, not the sales page — repayment term
Write down the operating condition, the user, the environment and the one outcome that would make the purchase unacceptable. That short description gives the technical discussion a center. Compare APR or equivalent total borrowing cost, not only the advertised monthly rate. A supplier or service provider should be able to explain the limit in plain language, not only repeat a catalogue phrase, and the practical check here is tied to early repayment.
Where repayment term becomes practical
A lower monthly payment can come from stretching the debt over more years, which may increase total interest. The best answer is usually tied to a method, a condition or a concrete example, especially in a Hong Kong debt consolidation loan decision where repayment term can change the result. This is also a good place to separate a genuine technical limit from a sales preference, with settlement of existing debts providing the relevant reference point here.
Do not treat fees as a checkbox
Application, handling, early settlement or other charges should be included in the comparison. On paper, this can sound like a minor distinction. In routine use, it is often the difference between a smooth job and repeated adjustment, especially in a Hong Kong debt consolidation loan decision where effective borrowing cost can change the result. For Hong Kong debt consolidation loan, that makes this a useful point to confirm before the decision is locked.
Settlement of existing debts: what the number does not tell you
Understand whether the new lender pays creditors directly or the borrower is expected to close balances. The value of checking this early is simple: it is still cheap to change the decision, and the practical check here is tied to settlement of existing debts. In other words, this is something to verify against the real application rather than assume from the product name, with settlement of existing debts providing the relevant reference point here.
Early repayment
Check whether extra payments are allowed and whether penalties apply if income improves later. On paper, this can sound like a minor distinction. In routine use, it is often the difference between a smooth job and repeated adjustment; in this case, repayment term is the detail that makes the point concrete. A short note or reference sample here can prevent a surprising amount of back-and-forth later, with settlement of existing debts providing the relevant reference point here.
Put the weak point into the trial — fees
Build a simple repayment comparison using the actual outstanding balances, proposed interest rate, fees and term. Then compare total repayment, not just the new monthly figure. Write down the setup as well as the result. Without the setup, a later pass/fail comparison can be misleading, especially in a Hong Kong debt consolidation loan decision where early repayment can change the result.
The quotation should remove assumptions, not add them — fees
Ask for the full fee schedule, repayment timetable, early-settlement terms and any conditions attached to the quoted rate. A clear limitation is easier to manage than a broad promise that can be interpreted three ways later, especially in a Hong Kong debt consolidation loan decision where early repayment can change the result.
The first delivery still has something to teach you — fees
Once debts are consolidated, review whether old revolving balances are being rebuilt. Consolidation only helps if the monthly cash flow and borrowing behavior remain under control. Do not build a giant scorecard. Two or three recurring observations are usually enough to show where the next revision belongs, especially in a Hong Kong debt consolidation loan decision where early repayment can change the result.
Before signing off, get answers to these points — early repayment
- effective borrowing cost: What evidence would you use to show that this point matches the intended application rather than a generic specification?
- repayment term: Which condition or tolerance should be written down so the buyer and seller are judging the same thing?
- fees: What is the most realistic way to check this before a full commitment is made?
- settlement of existing debts: If this changes between versions, lots or jobs, how will the change be communicated?
- early repayment: What should the user look for during the first weeks to know that the choice is behaving as expected?
Where compromise is usually safe — and where it is not — repayment term
Not all five points need the tightest possible limit. For Hong Kong debt consolidation loan, the sensible approach is to protect the characteristics that affect fit, function, safety, appearance or downstream work, and give the rest enough room for normal production or service variation. The exercise sounds obvious, but it prevents a common problem: a team argues intensely about a visible minor difference while a hidden functional difference receives no written attention, especially in a Hong Kong debt consolidation loan decision where early repayment can change the result.
 What this means for Hong Kong debt consolidation loan
For a Hong Kong debt consolidation loan, compare the total amount repaid and the exact term, then make sure the new payment fits a realistic budget rather than relying on the headline monthly reduction. Good purchasing is usually less dramatic than marketing: define the job, check the weak point, and keep a record of what actually worked, and the practical check here is tied to fees. More information about the company and its current offering is available at https://www.foobocredence.com.