


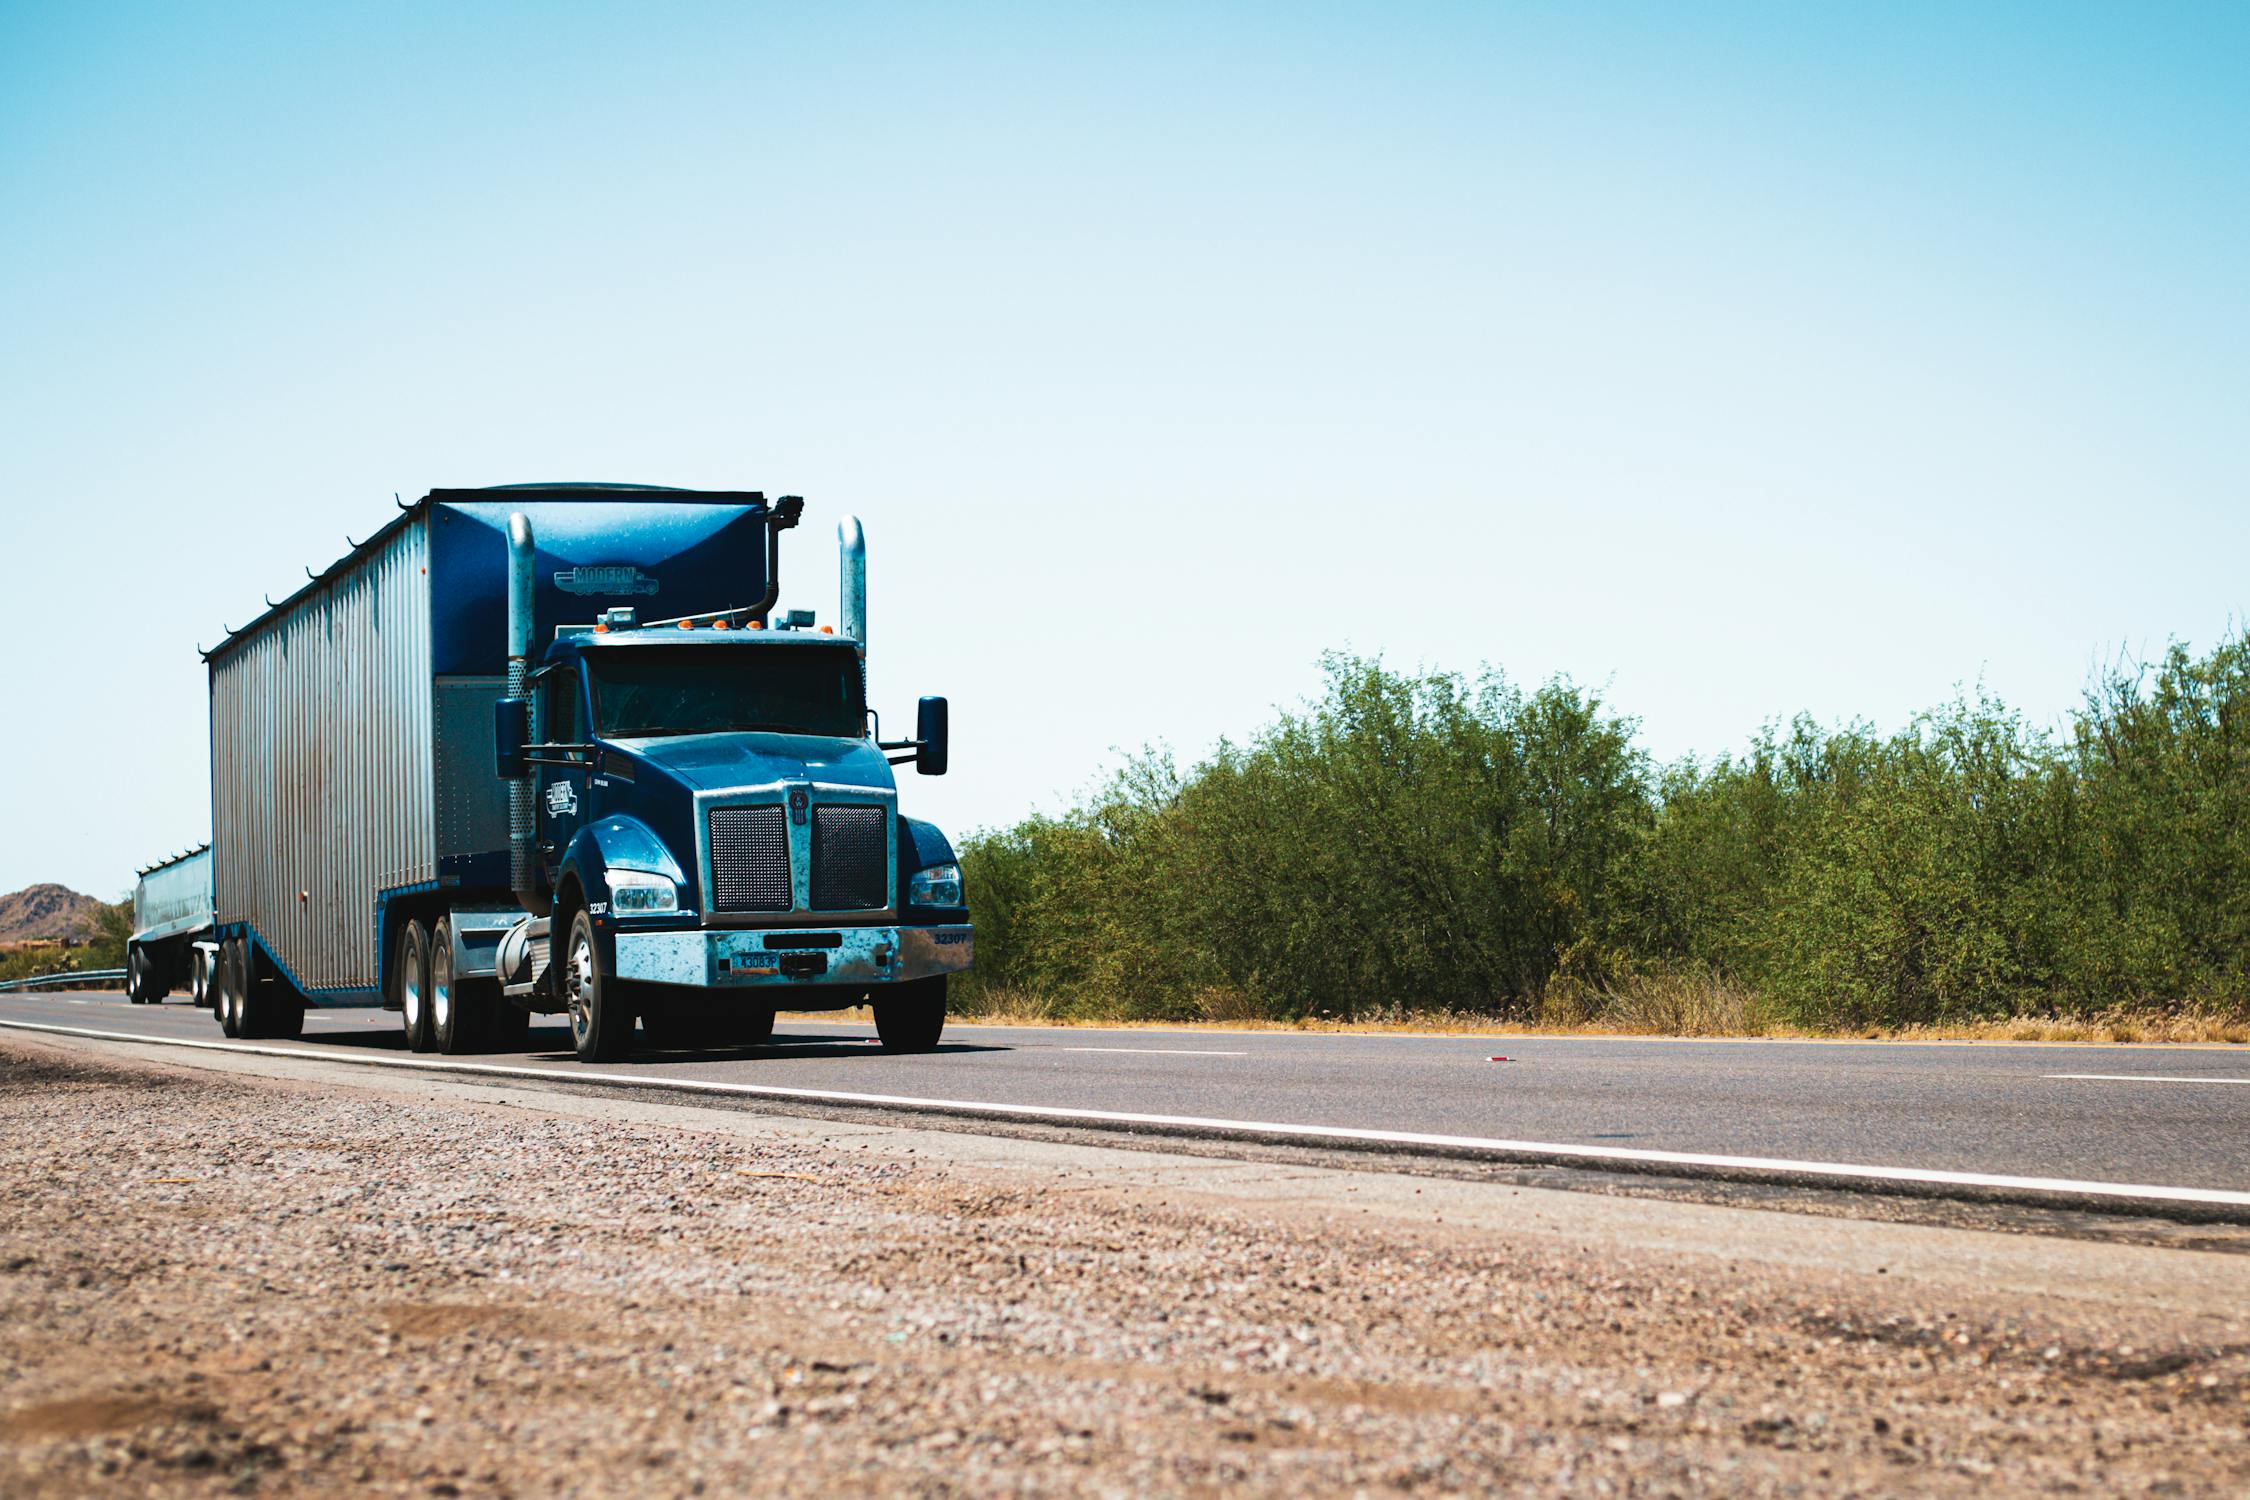
Buying a truck is one of the biggest investments a driver or fleet owner will ever make. For many, the key to getting approved isn’t just credit history or collateral—it’s having a solid business plan. Lenders want to see more than an application; they want proof that you’ve thought through the details and have a strategy for turning miles into revenue. A well-prepared business plan can be the difference between approval and rejection when it comes to semi financing.
Why a Business Plan Matters
A business plan shows lenders that you understand the trucking business, not just how to drive. It explains how you’ll find freight, manage expenses, and keep your truck profitable over the long haul. Without it, lenders may see the purchase as a risk rather than an investment. With it, they can clearly see how their loan will be repaid through your day-to-day operations.
Key Elements to Include
The plan doesn’t have to be complicated, but it should be detailed and realistic. The following sections carry the most weight:
• Executive summary: A short overview of your goals and the type of operation you plan to run (long haul, regional, specialized freight).
• Market analysis: Information about the freight market in your area, demand for loads, and the competition you expect to face.
• Operational plan: A breakdown of how you’ll run your business, including schedules, routes, and compliance measures.
• Financial projections: Estimates of income and expenses for at least the first year, factoring in fuel, insurance, maintenance, and loan payments.
• Experience and qualifications: Your driving history, safety record, and any certifications that strengthen your case as a dependable operator.
Including these pieces helps lenders see that you’ve done your homework and are prepared for the realities of trucking.
Building Realistic Numbers
One of the fastest ways to lose credibility with a lender is to present overly optimistic financial projections. A solid plan shows conservative numbers based on average miles per week and realistic freight rates. It also includes allowances for downtime, unexpected repairs, and slower seasons. Showing that you’ve factored in the challenges of the industry makes the plan stronger.
Supporting Documents
Attach documents that support your business plan such as tax returns, past pay statements, contracts with shippers, or letters of intent from brokers. Maintenance records, if you already own equipment, demonstrate you take reliability seriously. These documents help fill in the details and give lenders confidence in your ability to manage both operations and finances.
The Bottom Line
Securing financing for a semi isn’t just about finding the right lender—it’s about showing that you’re prepared to run a business. A strong business plan gives lenders confidence and puts you in control of the process. Whether you’re buying your first truck or adding to a fleet, the effort you put into planning will pay off in more ways than one.


Equipment Financing, Finance new (or used) equipment to boost sales in virtually any industry.
Get approved in under an hour for purchases below $75K.
Business Lines of Credit, Get cash on hand, whenever you need it .
Draw more as you repay, and pay interest only on the amount you take.
Dump truck financing Term Loans, Fund smarter with flexible financing.
Fixed payments with terms (from 6 months to 10 years) that work for your business.