

Navigating the Worldwide Seborrheic Dermatitis Treatment Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global seborrheic dermatitis treatment market has matured into a substantial and steadily expanding commercial landscape. Revenue reached approximately $2.5 billion in 2025, with the sector projected to cross $3.5 billion by 2032. The historical performance from 2020 through 2025 demonstrates consistent growth, while the forward outlook suggests a compound annual growth rate of 5.14 percent. This trajectory reflects a market that is no longer experiencing sudden spikes but rather compounding value through incremental therapeutic innovation, expanding product access, and persistent patient demand across diverse age groups.
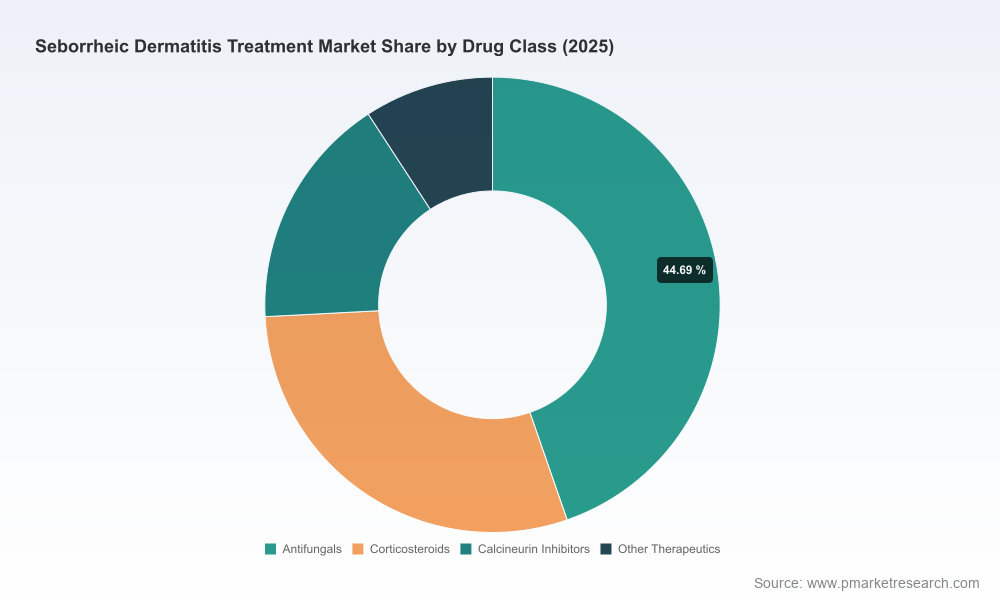
Despite this predictable expansion, several structural pressure points are reshaping how companies approach product development and commercial execution. The first challenge lies in the tension between established therapeutic dominance and the limits of clinical differentiation. Topical antifungals and corticosteroids continue to anchor first-line management, yet their long-term use is frequently constrained by tolerability concerns, recurrence patterns, and patient expectations for gentler options. Manufacturers operating within these legacy categories must navigate an environment where efficacy is expected rather than celebrated, making brand perception and formulation design increasingly important competitive levers.
A second challenge emerges from the shifting regulatory and reimbursement landscape. The market is transitioning toward newer non-steroidal mechanisms that promise targeted inflammation control without the steroid-related drawbacks that have historically limited adherence. However, access for these innovations depends heavily on formulary placement, payer familiarity, and clinician confidence. Prescription products entering the space must demonstrate not only clinical value but also real-world persistence and safety durability, especially when positioned against well-known OTC and prescription comparators.
A third challenge concerns generic supply dynamics and margin erosion. The availability of multiple manufacturers producing established topical antifungals has created a highly accessible price environment, particularly in mature markets where switching costs are low. At the same time, raw material supply concentration for key active ingredients remains geographically anchored, exposing product pipelines to logistics, cost variability, and capacity fluctuations. The combined effect is a market where healthcare providers, consumers, and payers have grown comfortable with familiar solutions, while innovators must justify the incremental cost and clinical change associated with newer entrants.
Taken together, these forces create a market that is large enough to sustain broad participation, yet selective enough to reward companies with differentiated mechanisms, strong commercial execution, and clear reimbursement narratives. Growth is likely to remain measured rather than explosive, which means strategic positioning will matter as much as product performance.
Key Drivers Shaping the Market
Therapeutic Innovation Beyond Established Mechanisms
One of the most consequential drivers is the emergence of non-steroidal topical options that address the recurring nature of seborrheic dermatitis without relying on corticosteroids. A PDE4 inhibitor foam recently entered the market as the first non-steroidal topical approved for this condition in more than twenty years, representing a meaningful mechanism shift. Sustained clinical data extending across multiple months has reinforced the product narrative around long-term management, which matters in a disease where maintenance and relapse prevention are central to patient value.
This innovation wave is changing how dermatology treatment is evaluated from both a clinical and commercial perspective. Instead of competing solely on potency or rapid onset, newer entrants are emphasizing tolerability, steroid-free positioning, and suitability for broader age groups. For companies developing or licensing topical therapies, the implication is clear: differentiation increasingly depends on how well a product supports chronic use, minimizes adverse concern, and fits into prescriber routines. The availability of long-duration safety and efficacy data strengthens the case for adoption, particularly when clinicians are seeking alternatives for patients who cannot tolerate or prefer to avoid traditional steroid regimens.
Regulatory Momentum and Access-Driven Adoption
Regulatory milestones and reimbursement inclusion are acting as powerful accelerators. The introduction of a novel mechanism has drawn attention to the possibility that seborrheic dermatitis can be managed with advanced prescription therapies rather than being confined to routine OTC solutions. Expanded approvals in additional geographies further reinforce the product’s commercial footprint, while formulary inclusion by major pharmacy benefit managers and growing visibility in public insurance programs create a more favorable access environment. Grinding Media Market
This dynamic underscores a broader lesson for the market: innovation alone does not guarantee commercial traction. Even clinically differentiated products must align with payer expectations, distribution pathways, and prescribing habits. In practical terms, companies that pair mechanism novelty with access strategy—whether through formulary negotiation, titration to real-world prescribing, or patient support frameworks—gain a structural advantage. This pattern is likely to influence how future dermatologic innovations are launched, especially in conditions where longstanding OTC alternatives already define consumer behavior.
Demand-Side Shifts in Patient Expectations
Patient and consumer expectations are also evolving in ways that pressure incumbents and create room for new value propositions. Seborrheic dermatitis is often associated with visible flare-ups, scalp discomfort, and recurring embarrassment, which makes adherence and cosmetic acceptability highly relevant. Patients increasingly look for options that minimize dependency on steroids, reduce irritation, and fit into simple application routines. This is true across both prescription and over-the-counter channels, where familiarity with active ingredients does not automatically translate into satisfaction or persistence.
At the same time, awareness of dermatologic conditions is improving, supported by broader consumer education and access to online health information. This can drive earlier consultation, more consistent treatment-seeking behavior, and demand for formulations that feel modern rather than purely utilitarian. For manufacturers, that means product experience—texture, scent, ease of use, and perceived gentleness—can be as commercially important as the active ingredient itself. Companies that ignore user experience risk losing share to competitors who may offer comparable efficacy but a more tolerable daily usage profile. PW Consulting
Supply-Side and Cost Structure Dynamics
On the supply side, the market continues to be shaped by the dominance of a limited number of API-producing regions and the resulting cost architecture for topical antifungals. India and China remain central to global production of ketoconazole active pharmaceutical ingredient, with Indian manufacturers exporting to a wide set of international markets. This concentration helps keep supply accessible, but it also introduces sensitivity to manufacturing disruptions, regulatory changes, and cost variability.
At the formulation level, the presence of multiple generic suppliers for established antifungal shampoos and creams has intensified price competition in mature segments. Lower pricing improves accessibility for patients and healthcare systems, yet it places pressure on originators and branded manufacturers to defend margins through product differentiation, lifecycle management, or premium positioning. For generic producers, scale efficiency and regulatory compliance become the primary differentiators, while branded players must justify premium access through clinical novelty or superior treatment experience. The balance between affordability and innovation will remain a defining feature of the market’s cost structure through the forecast period.
Competitive Landscape and Leading Strategies
The competitive field in seborrheic dermatitis treatment spans legacy branded portfolios, established consumer and dermatology franchises, and a growing cohort of generic manufacturers. A handful of companies have built particularly visible positions by emphasizing either mechanism innovation, formulation breadth, or global generic reach. Arcutis Biotherapeutics stands out for its focus on a steroid-free PDE4 inhibitor foam with expanded-age approval and long-term safety data, supported by method-of-treatment intellectual property extending into the next decade. This position gives the company a defensible product narrative centered on a differentiated mechanism and a maintenance-oriented clinical profile. Arthroscopy Irrigation Pumps Market
Larger diversified players continue to rely on breadth and distribution strength. Johnson & Johnson maintains relevance through legacy antifungal and medicated shampoo and cream offerings, including well-known ketoconazole-based products. GlaxoSmithKline and Bayer contribute through antifungal and corticosteroid topicals that fit into established treatment routines, while Merck and Novartis supply dermatology-adjacent antifungal and anti-inflammatory products that can be incorporated into broader clinical regimens. These companies benefit from strong brand recognition, existing sales infrastructure, and the ability to cross-sell across dermatology and consumer categories.
The generic side of the market is equally important and increasingly competitive. Indian manufacturers such as Sun Pharmaceutical Industries, Aurobindo Pharma, and Lupin, along with Teva, Hikma, and recently approved entrants like Zydus Lifesciences, maintain a strong presence in ketoconazole shampoos and topical antifungal formulations. Their strategic advantage lies in scale manufacturing, regulatory clearance speed, and the ability to supply multiple markets at competitive prices. In recent years, generic approvals and launches for key OTC and prescription strengths have intensified price competition within the established antifungal segment, reinforcing the margin pressure on incumbents and expanding access for patients and healthcare systems.
The market structure is best understood as moderately concentrated at the top, with several players competing across both legacy and innovation-led segments. This creates space for parallel strategies: branded innovators can pursue differentiated therapeutic positioning and premium access, while generic producers can focus on cost leadership, supply reliability, and geographic breadth. Over time, the landscape is likely to evolve through incremental consolidation among commercial players, increased competition from new mechanism entrants, and continued fragmentation in generic supply. Companies that succeed will be those that define a clear lane—whether that is clinical novelty, form factor advantage, reimbursement alignment, or manufacturing efficiency—rather than trying to compete on every axis at once.
Future Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by a gradual shift toward steroid-sparing management, stronger emphasis on maintenance and adherence, and continued pressure on legacy antifungal pricing. As non-steroidal prescription options gain familiarity, clinicians and patients may become more comfortable with longer-duration use of advanced topical therapies, especially when long-term data supports safety and relapse control. This creates a commercial opportunity for products that can position themselves as both effective and sustainable for chronic management, rather than short-term flare control alone.
A second trend is the rising commercial relevance of user experience and formulation design. In a condition where daily application, cosmetic feel, and scalp or skin tolerability influence persistence, products that combine meaningful mechanism differentiation with pleasant, easy-to-use delivery formats are better positioned to retain share. This may encourage both branded and generic players to invest more in formulation quality, delivery systems, and packaging designed for routine use. Even in price-sensitive segments, a superior application experience can become a retention advantage when clinical differences are modest.
A third trend is the expanding role of access strategy as a competitive differentiator. With major pharmacy benefit managers and public formularies showing growing openness to newer options, the ability to secure coverage, support prescribing confidence, and reduce practical barriers to use will increasingly determine commercial outcomes. At the same time, raw material supply concentration and generic price erosion will continue to reward companies that can manage cost structure efficiently while preserving margin in differentiated categories. The main uncertainty lies in how quickly payers, clinicians, and patients adopt newer mechanisms in real-world settings, and whether future neurological or dermatologic entrants can sustain pricing power as competition intensifies.
Strategic Recommendations for Decision-Makers
For manufacturers and developers, the priority should be building a clear differentiation thesis that ties mechanism or formulation advantage to a patient-centric outcome such as tolerability, adherence, or reduced steroid reliance. Products that can demonstrate durable use, comfortable application, and credible access pathways will stand out more effectively than those competing only on ingredient heritage. Lifecycle planning also matters: as generic competition intensifies in established antifungal categories, brand builders should prepare for margin shifts and consider how innovation, reformulation, or new indication narrative can protect value.
For investors, the most meaningful signals are regulatory approvals that broaden eligible populations, long-term clinical data that support maintenance use, and reimbursement developments that confirm access. Companies that combine a differentiated mechanism with growing formulary presence and intellectual property protection deserve closer scrutiny, especially when they are positioned to benefit from a shift toward steroid-sparing care. At the same time, caution is warranted in segments where price erosion from multiple generic suppliers is already compressing returns and where supply chain concentration could affect cost predictability.
For procurement and formulary decision-makers, the decision calculus should balance clinical novelty, real-world tolerability, and total cost of ownership rather than relying solely on ingredient familiarity. As newer options become more accessible, evaluating persistence, adverse-effect profile, and formulary alignment can improve outcomes while reducing hidden costs associated with nonadherence or repeated flare management. More detailed segmentation data, pricing dynamics, and competitor-specific commercial models can help convert these market-level observations into targeted sourcing and portfolio decisions. Readers seeking a more granular view of regional splits, drug-class detail, dosage-form dynamics, and competitor positioning can turn to the full market study for a deeper dive and customizable strategic guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Seborrheic Dermatitis Treatment Market
Lacy LeeSenior Marketing Managersales@pmarketresearch.com00852-95632430PW Consulting: www.pmarketresearch.com
Seborrheic Dermatitis Treatment Market Size is expected to cross USD 3.28 Billion by 2025 at a CAGR of 10.5 % and Region (Americas, Europe, Asia-Pacific and the Middle East & Africa) - Forecast till 2025Global Seborrheic Dermatitis Treatment Market Size In-Depth competition analysis of the major companies in the report, sector of the report includes the market depictions, requirements, and product portrayals, manufacture, competence, contact figures, cost, and revenueMajor Key PlayersThe key strategies followed by the players operating in the global Seborrheic Dermatitis Treatment Market Size were innovation, product development, acquisition, and expansion.Sonoma Pharmaceuticals (US), Merck (US), Hikma Pharmaceuticals (UK), Allen and Hanburys (UK), GlaxoSmithKline (UK), Bausch Health (Canada), Valent Pharmaceutical (UK), and West-Ward Pharmaceutical Corp. (US) Market Segment AnalysisThe global Seborrheic Dermatitis Treatment Market Size has been segmented based on treatment type, route of administration, and end user.The market, based on treatment type, has been divided into antifungal products, corticosteroid lotions, and sulfur products.
Around 1.5 million Americans are diagnosed with various seborrheic dermatitis every year.
The global Seborrheic Dermatitis Treatment Market Size has been segmented, on the basis of route of administration, oral, and topical.
Around 25 million adults are diagnosed with chronic seborrheic dermatitis every year, and most of them treated with the help of oral drugs.
The topical segment is expected to be the fastest-growing due to its increasing use globally.
It was estimated that around 1.3 million people in the US were afflicted with seborrheic dermatitis in 2018.The end-user segments of the market are hospital pharmacies, retail pharmacies, and others.