

Navigating the Worldwide Military Cyber Range Solutions Market: Strategic Trends and Commercial Opportunities
Market Snapshot: Scale, Momentum, and Critical Headwinds
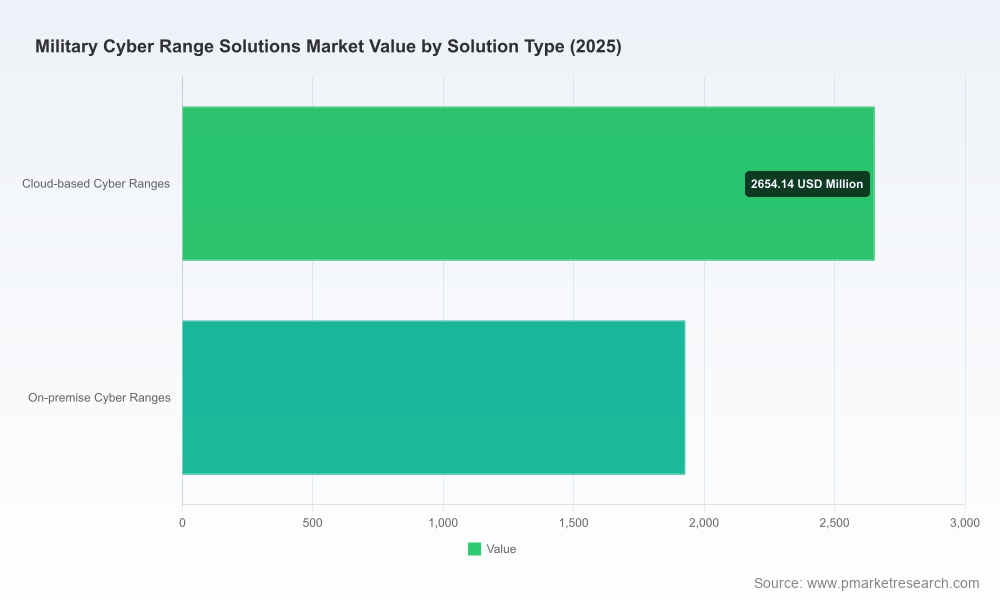
The global military cyber range solutions market has evolved from a niche procurement category into a strategic infrastructure priority for defense organizations worldwide. Valued at approximately $2.41 billion in 2020, the sector has grown consistently to surpass $4.58 billion by 2025, and forward projections point toward a trajectory that will push the market well past the $10 billion threshold by 2032. This expansion is underpinned by a compound annual growth rate of roughly 13.3 percent across the forecast window, signaling sustained institutional demand rather than a temporary defense spending anomaly. Cyber ranges have transitioned from experimental training environments to mission-critical platforms that validate operational readiness, stress-test defensive architectures, and enable complex scenario rehearsal across joint and coalition forces.
Despite the favorable trajectory, the market is navigating structural inflection points that will separate strategic winners from passive participants. First, the sheer scale and fidelity requirements of modern military cyber training are colliding with infrastructure realism constraints. High-concurrency emulation, persistent threat replication, and geographically distributed exercises demand computing, networking, and storage architectures that many legacy procurement models were never designed to support. As training scenarios grow more dynamic and multi-domain, platforms that cannot scale without sacrificing scenario authenticity or introducing unacceptable latency will face rapid obsolescence. Second, data sovereignty and jurisdictional compliance are reshaping procurement pathways. Defense organizations increasingly require training data, mission profiles, and emulation workloads to remain under national or coalition control, which complicates cloud adoption and forces vendors to design segmented deployment models, hardened hosting environments, or sovereign cloud arrangements. Third, the market is maturing into a more consolidated competitive space where value is shifting from standalone platform licenses to integrated readiness ecosystems. Buyers are evaluating how well a cyber range connects with broader cyber operations tooling, intelligence workflows, and mission rehearsal pipelines, which puts pressure on vendors to demonstrate interoperability rather than isolated feature sets.
These dynamics create both risk and opportunity. Organizations that treat cyber ranges as fixed training utilities may underestimate the pace at which scenario complexity, distribution requirements, and compliance expectations will escalate. Conversely, stakeholders who align platform strategy with evolving operational demands can secure durable positioning in a market where readiness, validation, and rehearsed response are becoming central to defense planning.
Key Drivers Reshaping the Market
Technological Innovation and High-Fidelity Emulation
The most consequential driver of market growth is the push toward higher-fidelity, larger-scale cyber emulation. Military cyber ranges are no longer limited to isolated laboratory exercises; they are expected to simulate contested networks, replicate adversary tactics at scale, and support thousands of concurrent participants in live-fire style training. This shift is fueled by advances in virtualization, orchestration, and scenario automation, which enable platforms to replicate complex enterprise and tactical environments with greater realism. AI-assisted scenario generation and automated range configuration are further accelerating the pace at which new training narratives can be designed, adapted, and redeployed. The result is a marketplace where differentiation increasingly depends on how realistically a platform can mirror operational conditions and how quickly it can translate new threat intelligence into executable training scenarios. PW Consulting
At the same time, infrastructure demands are intensifying. High-fidelity cyber range operations draw heavily on compute, storage, and low-latency networking, and broader data center energy consumption trends are a relevant macroeconomic signal for planners evaluating long-term operating costs. The expansion of AI workloads and cloud-connected services across the wider digital economy is increasing pressure on power and cooling capacity, which indirectly affects the cost structure and site selection logic for large-scale cyber training environments. For military programs, this means that range architectures must balance simulation depth against operational efficiency, and vendors that can deliver realistic training without unsustainable infrastructure overhead will gain a meaningful advantage.
Policy, Security Mandates, and Sovereignty Requirements
Regulatory and policy frameworks are becoming a decisive force in shaping deployment models. Defense and government buyers are operating in environments where data handling, cross-border access, and mission-sensitive information storage are subject to tightening sovereignty expectations. This is driving interest in hardened hosting, encrypted or segmented cloud architectures, and air-gapped configurations for the most sensitive training profiles. In parallel, broader digital economy regulations in major markets are reinforcing expectations around technological independence and secure data governance, which influences how multinational vendors structure their offerings for defense customers. The commercial implication is clear: platforms that can offer flexible deployment options and demonstrate rigorous control over where training data resides and how it is processed will face fewer procurement friction points.
Demand-Side Shifts Toward Mission Readiness and Coalition Operations
On the demand side, military organizations are moving beyond periodic training cycles toward persistent readiness validation. Cyber mission forces, security operations teams, and weapon system testers increasingly require environments where tactics, techniques, and procedures can be rehearsed repeatedly under evolving threat conditions. Coalition exercises and allied interoperability add another layer of complexity, as ranges must support distributed participation, shared scenario standards, and multi-national data handling rules. This demand pattern favors platforms that can support recurring exercises, scale across units and domains, and integrate with broader mission rehearsal workflows. It also encourages procurement teams to view cyber ranges as enablers of operational continuity rather than isolated training purchases.
Supply Chain and Connectivity Considerations
Underlying infrastructure and connectivity are becoming strategic variables rather than background assumptions. Tactical and distributed cyber range deployments increasingly rely on resilient networking backbones that can be stood up quickly in austere or operational environments. Portable fiber and ruggedized network equipment are enabling ad-hoc secure backbones for cyber and IoT-heavy training settings, reducing the time required to establish functional range infrastructure in the field. At the same time, long-haul connectivity dependencies are drawing attention to the strategic importance of submarine cable networks and the limited capacity of cable-laying resources, which can affect the reliability and cost of globally distributed range operations. Defense planners and vendors alike are therefore factoring physical connectivity, deployment speed, and supply chain resilience into range architecture decisions.
Competitive Landscape and Strategic Positioning
Divergent Models Among Leading Providers
The market includes a broad mix of specialized cyber range vendors, defense-adjacent integrators, and large aerospace and security organizations extending into cyber training and mission rehearsal. Specialized providers are typically competing on fidelity, scenario depth, and cohort scale. Some have built platforms designed to support very large concurrent emulation environments for elite force training and intelligence community use, while others emphasize automated scenario design, persistent training, and AI-assisted range configuration. These vendors often position themselves as focused solutions for government and military buyers who need high realism, repeatable mission rehearsal, and tailored exercise support.
At the same time, several defense-oriented players are leveraging broader platform portfolios and mission-system expertise to embed cyber range capabilities into larger readiness ecosystems. Their advantage often lies in integration with existing defense programs, instrumentation, and multi-domain rehearsal context. This creates a market where buyers compare not only training quality but also how well a solution fits within wider cyber operations, testing, and validation workflows. The presence of cloud-oriented and as-a-service models further broadens the competitive field, giving procurement teams alternatives between fully managed environments and on-premise or hybrid deployments. Face Recognition Systems Market
Recent Developments as Indicators of Market Direction
Recent activity highlights how vendors are adapting to changing buyer expectations and operational needs. One notable pattern is the push toward ecosystem integration: a leading cyber range provider partnered with a defense platform company to embed its range environment into a broader defense platform for training, testing, and validation of cyber defense workflows, with initial relevance to allied governments and regional defense partners. This type of move signals that competitive advantage is increasingly tied to interoperability and workflow integration rather than standalone range capability.
Another trend is the expansion of training infrastructure through partnerships and campus-scale deployments that extend the reach of cyber defense ranges into academic and government-relevant environments. By linking virtual enterprise network training with real tools and dedicated government and military offerings, providers are broadening the pipeline for team readiness in detection and response. On the institutional side, dedicated cyber range squadrons and modernization programs are reinforcing the idea that cyber ranges are becoming formal organizational assets. The activation of a space force cyber range squadron focused on aggressor functions and distributed range environments, alongside broader network modernization efforts to replace legacy copper with secure low-latency fiber, illustrates how range operations are being institutionalized and linked to upgraded connectivity.
Consolidation, Fragmentation, and the Entry Barrier Debate
The competitive structure is likely to evolve along two parallel paths. In one direction, consolidation may accelerate as larger defense and technology organizations seek to aggregate cyber training, simulation, and mission rehearsal capabilities under unified platforms. In the other, fragmentation may persist at the solution level, with niche providers continuing to win on specialized scenario design, coalition exercise support, or domain-specific training needs. Entry barriers are rising for generic platforms because buyers increasingly expect high concurrency, realistic threat emulation, secure deployment flexibility, and integration with existing cyber operations tools. That favors incumbents with proven scale and defense-facing credentials, while also leaving room for agile specialists that can deliver differentiated scenario content, faster exercise setup, or superior usability for specific training audiences. Worldwide EMV Smart Cards Market
Market concentration also suggests that the largest providers hold meaningful share, but not dominance severe enough to preclude decisive competition. With the top three and top five players accounting for a substantial but not overwhelming portion of revenue, there is still space for strong positioning by vendors that can demonstrate unique value in readiness validation, scenario realism, or sovereign deployment models. The practical takeaway is that competitive strategy should be built around integration, deployment flexibility, and exercise relevance rather than feature count alone.
Forward Outlook: Trends That Will Define the Next Three to Five Years
Readiness-Centric Range Ecosystems
Over the next several years, cyber ranges are likely to be evaluated less as training platforms and more as readiness-validation ecosystems. Expect growing emphasis on continuous exercise cycles, scenario libraries that update in response to emerging threat activity, and tighter linkage between range outputs and operational improvement loops. Providers that can help defense organizations turn training into measurable readiness gains, rather than episodic certification events, will capture stronger strategic relevance. The commercial opportunity here lies in services, content updates, scenario engineering, and analytics that connect exercise performance to operational planning.
Sovereign, Hybrid, and Distributed Deployment Models
Deployment architecture will become a core differentiator. As data sovereignty expectations and jurisdictional control requirements intensify, vendors will need to support sovereign cloud environments, segmented hosting, and secure hybrid configurations that satisfy national control requirements without sacrificing scalability. Distributed range models will also gain importance for coalition exercises and geographically dispersed forces. Organizations that can offer flexible sovereignty-aligned deployment options, while maintaining consistent scenario quality across locations, will be better positioned for international and multi-domain programs. The associated risk is cost and complexity: sovereign and hardened deployments can raise operating expenses and slow rollout timelines if not architected efficiently.
Infrastructure Efficiency as a Competitive Variable
Because high-fidelity range operations place heavy demands on compute, networking, and power, efficiency will become a strategic variable rather than a back-office concern. Suppliers that can deliver realistic emulation with lower energy and infrastructure intensity, or that can integrate cleanly with modernized fiber and distributed network backbones, will face fewer procurement hurdles and lower total ownership friction. Conversely, programs that ignore infrastructure sustainability may encounter budget pressure, site constraints, or deployment delays as energy and connectivity capacity become tighter constraints. A related uncertainty is the pace of modernization: network upgrades and data center capacity expansion do not happen uniformly across regions, which could create uneven readiness for large-scale range adoption.
Strategic Recommendations for Decision-Makers
For Platform Providers and Technology Manufacturers
Invest in interoperability and deployment flexibility as core product attributes. The market is rewarding solutions that connect cleanly with broader cyber operations workflows, support sovereign or segmented hosting, and can scale across distributed exercises without sacrificing scenario fidelity. Differentiate through scenario engineering quality, rapid exercise setup, and integration depth rather than through generic platform breadth. Monitor infrastructure efficiency as a design constraint, because operating cost and energy intensity will increasingly influence procurement decisions for large-scale range environments.
For Investors and Strategic Partners
Focus on players that demonstrate durable demand signals from defense and government buyers, recurring exercise relationships, and credible pathways to sovereign or hybrid deployment. Preference should lean toward organizations that are building ecosystem partnerships, expanding scenario libraries, and aligning with modernization programs that improve connectivity and range scalability. Be mindful of risk from infrastructure cost escalation, regulatory complexity, and the possibility of consolidation that could reshape vendor positioning. Due diligence should evaluate not only technology capability but also deployment economics and compliance readiness.
For Procurement and Program Leaders
Treat cyber range selection as a long-term readiness investment rather than a point solution purchase. Evaluate total ownership implications, including hosting model, data handling constraints, exercise scalability, and integration with existing cyber operations and testing workflows. Prioritize vendors that can support recurring mission rehearsal, adapt scenarios to evolving threat conditions, and provide clear pathways for sovereign or hybrid deployment where required. Ensure that network modernization and infrastructure planning are synchronized with range adoption, because distributed and high-fidelity exercises depend on secure, low-latency connectivity and realistic operating environments.
The strategic landscape is shifting too quickly for static procurement assumptions. Decision-makers who want to translate these trends into concrete plans will benefit from deeper segmentation, deployment-model analysis, and scenario-level insight that can be tailored to specific organizational contexts. A detailed research report can provide the structured data and procurement-relevant breakdowns needed to compare options with greater confidence and to align range strategy with longer-term readiness goals.
For detailed analysis of this topic, please visit the official page: Worldwide Military Cyber Range Solutions Market
Lacy LeeSenior Marketing Managersales@pmarketresearch.com00852-95632430PW Consulting: www.pmarketresearch.com
As we roll into a new decade, we must be prepared for the advances and the threats that come as a result of technological advancement.
The last decade saw an exponential rise in technological advancement including the development of the cloud, connected devices, the rise of AI and machine learning and many other developments that have shrunk the world and brought people closer.
But with this development have arisen many security risks and threats that will need to be dealt with.
As there is an increase in cyber-attacks daily on organizations and critical governmental installations, there is a need for updated cyber security incident response training programs and IT cyber security training that will help organizations, employees and all stakeholders to be prepared to deal with such attacks and to be able to safeguard important and critical data, and this is all the more critical for Law enforcement to be able to deal with such incidents which are raised on an almost daily basis.Why is this so?
Many experts believe that this will see an increase in the number of phishing attacks, and that organizations must step up their security mechanisms to be able to deal properly with these attacks.
As technology advances, it becomes much more easier to clone official emails and people, and organizations and employees can fall for such mails if they are not aware of the trends and have not received appropriate IT security training that has been updated for this year, and this can pose a huge problem for law enforcement, as they will have to deal with this threat.
Do you know how your team and your playbook will perform under extreme pressure?Almost 50% of companies and organizations with an IR playbook do not test it regularly, and most companies do not even have a response plan against a cyber-attack.
You get performance-based informationA run through a cyber range will provide access to real-time data, which is a huge advantage over exercises and simulations done through more traditional means.
Guidance from expertsYou can test your team against industry experts with years of experience in these kinds of situations.
Real-life learningMost cyber security experts know that graduates are not well prepared to deal with cyber security threats as soon as they enter the industry.
A simulation in the range is an excellent opportunity to give them some invaluable experience with no real repercussions.4.
Test possible team membersA cyber range simulation can be a good way of assessing potential hires and identifying potential candidates who come from a different background.5.